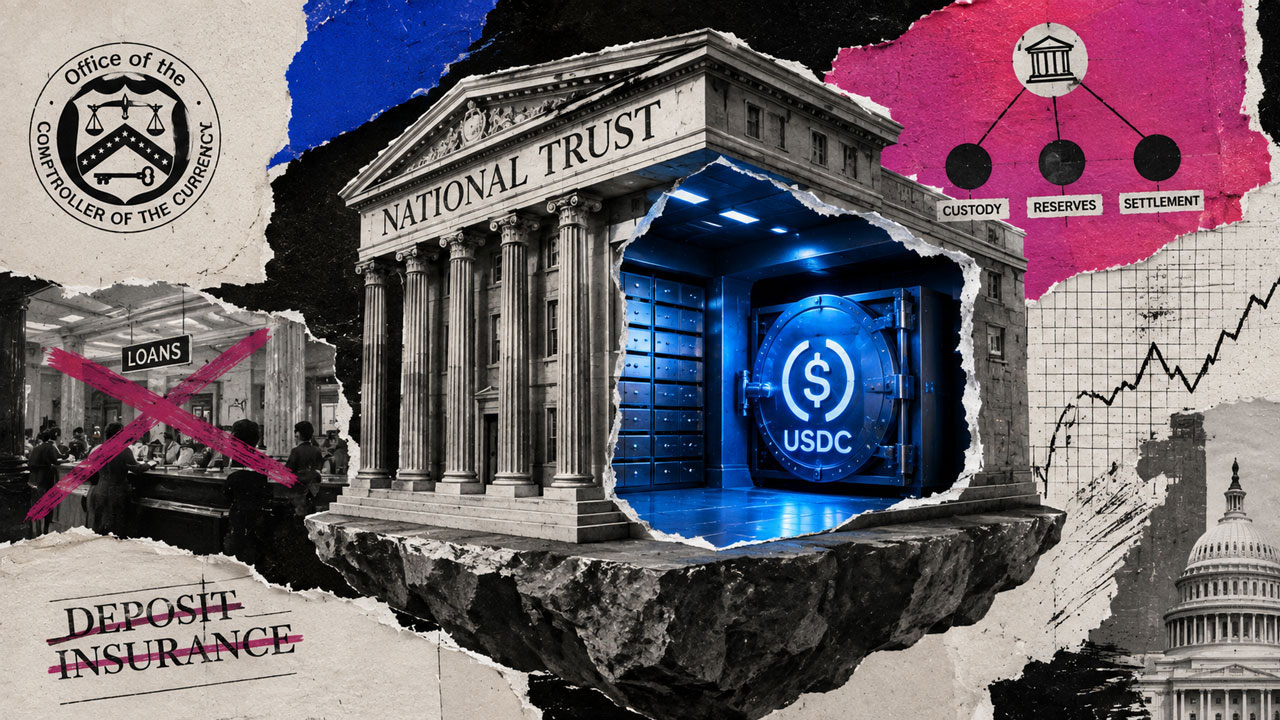
워싱턴은 암호화폐 기업에 은행의 법적 껍질을 부여하는 동시에 소비자가 일반적으로 은행에 기대하는 거의 모든 것을 제거하고 있습니다.
Circle은 이제 연방 은행 헌장을 보유하고 있습니다. 그러나 헌장은 일반 당좌 예금 계좌, FDIC 보장 저축 계좌 또는 모기지를 제공하지 않습니다.
Circle National Trust는 보관, 수탁 관리, 스테이블코인 준비금 및 결제를 중심으로 구축된 새로운 연방 집단의 일부입니다.
리플, Bit Go, Fidelity Digital Assets, Paxos, Bridge, 암호화폐. com, Coinbase, Morgan Stanley 및 World Liberty Financial은 모두 12월부터 통화 감사관실 승인을 받았습니다. 대부분은 아직 개봉 전에 요구되는 조건을 충족하고 있습니다.
워싱턴은 암호화폐 회사에 은행 업무의 규제 껍질을 제공하는 동시에 미국인들이 일반적으로 은행과 연관시키는 비즈니스 모델과 분리하고 있습니다. 그 결과 예금을 모아 이를 대출로 전환하는 고전적인 방식에 의존하지 않고 자산과 거래를 감독하는 협소한 기관이 탄생했습니다.
비은행 은행의 법적 형태는 실제로 암호화폐보다 우선합니다. OCC는 지난 12월 5개의 디지털 자산 신청을 승인했을 때 이미 약 60개의 국가 신탁 은행을 감독했다고 밝혔습니다. Morgan Stanley는 무보험 국가 신탁 은행에서 관리하는 자산을 7달러로 결정했습니다. 3월 31일 현재 1달러 포함 2조 달러입니다. 7조 달러의 보관 및 보관 계정. 암호화폐는 토큰에 가장 적합한 금융 부분을 포착하기 위해 기존 형식을 사용하는 방법을 찾았습니다.
상업 은행은 한 지붕 아래 여러 기능을 결합합니다. 예금을 모으고, 지불 계좌를 운영하고, 신용을 연장하고, 고객을 위해 자산을 보유합니다. 예금 보험은 자금 기반에 대한 신뢰를 지원하는 반면 대출은 수입의 대부분을 창출합니다.
그러나 국민신탁은행은 매우 다른 입장에서 출발합니다. 그 중심은 수탁 업무입니다. 즉, 다른 당사자를 위해 재산을 보유하고, 자산을 관리하고, 지시를 실행하고, 기록을 유지하는 것입니다. OCC의 신탁은행 지침에 따르면 대부분의 국가 신탁은행은 대출을 제공하지 않고, 예금도 받지 않으며, FDIC 보험도 가입하지 않습니다.
해당 모델은 디지털 자산에 잘 맞습니다. 기관에는 개인 키를 보호하고, 고객 자산을 분리하고, 토큰화된 자산을 관리하고, 이체를 기존 결제와 연결하기 위해 규제 대상 엔터티가 필요합니다. 스테이블코인 발행자는 또한 연방 조사를 견딜 수 있는 예비 보관 및 상환 작업이 필요합니다. 실제로 이러한 직업 중 어느 것도 소매 지점 네트워크나 모기지 장부가 필요하지 않습니다.
Circle은 이미 잘 규제되어 있으며 미국 시장에서 좋은 위치에 있습니다. OCC는 Circle National Trust로 운영될 First National Digital Money Bank에 대해 7월 10일 최종 승인을 받았습니다. 개장 시에는 Circle과 그 계열사에 대한 신탁 디지털 자산 관리권을 제공할 계획입니다. 선택된 기관에 대한 보관 및 USDC 준비금 관리는 가능한 미래 기능으로 나열됩니다.
암호화폐 Slate의 Circle 헌장에 대한 초기 조사에서는 "은행"이라는 단어가 일반 예금이나 대출 권한을 생성하지 않는 이유를 설명했습니다. 더 넓은 집단은 발행자, 관리인 및 금융 그룹을 포괄하는 연방 범주를 설정합니다.
TheOCC가 발표한 결정은 예비 또는 조건부 승인과 최종 승인을 구분합니다. 조건부 결정을 통해 신청자는 기관을 조직하고 자본, 거버넌스, 규정 준수 및 운영 요구 사항을 충족할 수 있습니다. 해당 조건이 충족되면 나중에 개봉됩니다.
원문 제목: America is creating a new class of crypto banks – but they aren’t really banks
Washington is giving crypto companies the legal shell of a bank while stripping away nearly everything consumers normally expect a bank to do.
Circle now has a federal bank charter. However, the charter provides no ordinary checking accounts, FDIC-insured savings accounts, or mortgages.
Circle National Trust is part of a new federal cohort built around custody, fiduciary administration, stablecoin reserves, and settlement.
Ripple, BitGo, Fidelity Digital Assets, Paxos, Bridge, Crypto.com, Coinbase, Morgan Stanley and World Liberty Financial have all received some form of Office of the Comptroller of the Currency approval since December. Most are still completing conditions required before opening.
Washington is giving crypto companies the regulatory shell of banking while separating it from the business model Americans usually associate with a bank. The result is a narrow institution that supervises assets and transactions without relying on the classic formula of collecting deposits and turning them into loans.
That legal form of a non-bank bank actually predates crypto. The OCC said it already supervised roughly 60 national trust banks when it approved five digital-asset applications in December. ItsMorgan Stanley decisionput assets under administration at uninsured national trust banks at $7.2 trillion as of March 31, including $1.7 trillion in custody and safekeeping accounts. Crypto has found a way to use that old form to capture the parts of finance best suited to tokens.
A commercial bank combines several functions under one roof. It gathers deposits, runs payment accounts, extends credit, and holds assets for customers. Deposit insurance supports confidence in the funding base, while lending produces much of the income.
A national trust bank, however, starts from a very different position. Its center of gravity is fiduciary work: holding property for another party, administering assets, executing instructions, and maintaining records. TheOCC's trust-bank guidancesays most national trust banks don't offer loans, accept deposits, or carry FDIC insurance.
That model fits digital assets well. Institutions need a regulated entity to safeguard private keys, segregate customer property, administer tokenized assets, and connect transfers with conventional settlement. Stablecoin issuers also need reserve custody and redemption operations that can withstand federal examination. None of those jobs actually requires a retail branch network or a mortgage book.
Circle is already well regulated and well positioned in the US market. The OCC grantedfinal approval on July 10for First National Digital Currency Bank, which will operate as Circle National Trust. At opening, it plans to provide fiduciary digital-asset custody for Circle and its affiliates. Custody for selected institutions and management of USDC reserves are listed as possible future capabilities.
CryptoSlate's earlier examination of Circle's charter explained whythe word “bank” doesn't create ordinary deposit or lending powers. The wider cohort establishes a federal category spanning issuers, custodians, and financial groups.
TheOCC's published decisionsseparate final approvals from preliminary or conditional ones. A conditional decision allows an applicant to organize the institution and satisfy capital, governance, compliance and operating requirements. Opening comes later, once those conditions are met.