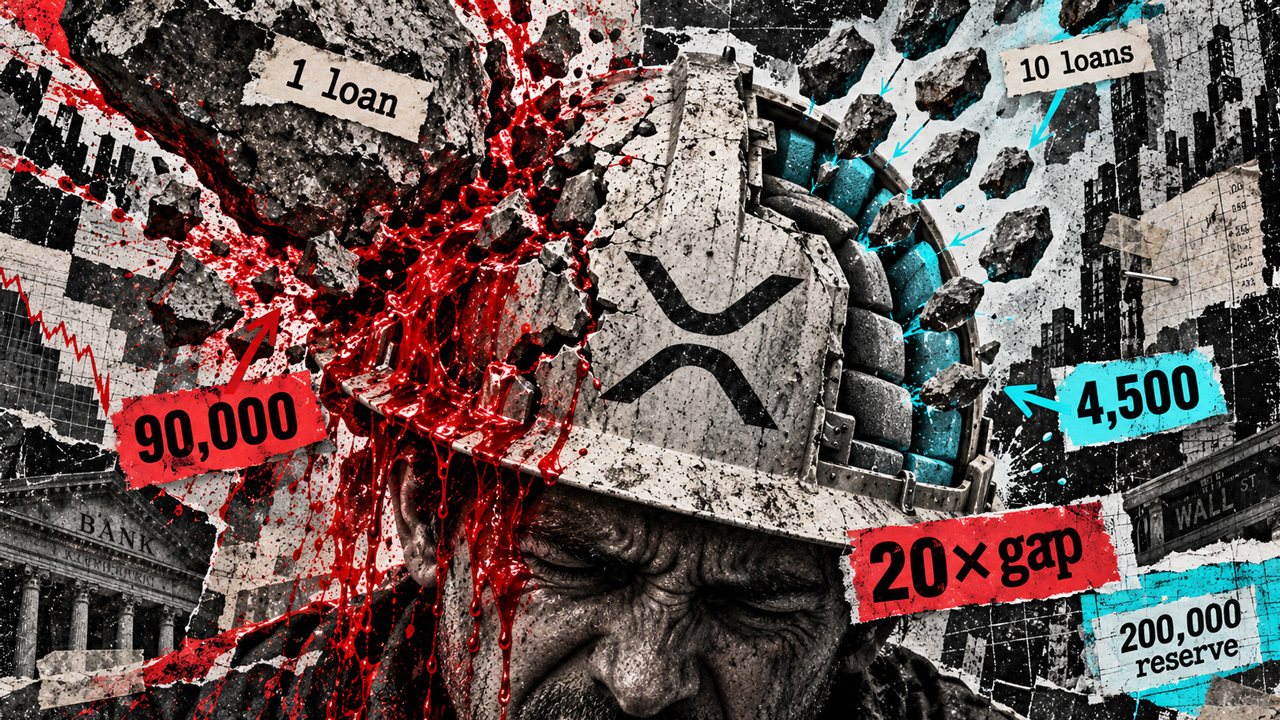
동일한 준비금 및 보장 비율을 사용하면 하나의 모델링된 기본값으로 인해 90, 000개의 토큰이 금고 손실됩니다. 10개의 작은 대출이 4, 500을 남깁니다.
모델링된 XRP Ledger 대출 장부에 있는 가치 지원 예금자의 지분은 하나의 대출이 불이행될 때 90, 000토큰으로 감소하는 반면, 동일한 100, 000개의 불량 부채 토큰이 10개의 작은 대출에 있을 때 4, 500토큰으로 감소합니다. 두 책 모두 100만 개의 부채 토큰, 200, 000개의 토큰 준비금 및 동일한 보호 설정으로 시작합니다.
20배의 격차는 문서화된 대출 규칙이 해당 적립금을 해제하는 방식에서 비롯됩니다. 각 기본값에는 별도의 적용 범위 계산이 적용됩니다. 따라서 총 미지급 부채와 이를 흡수할 수 있는 자본이 처음에 동일하게 유지되는 경우에도 대출 규모에 따라 예금자가 손실을 입는 정도가 달라집니다.
XRPL의 대출 설계는 자산을 금고에 풀링하고 인수를 담당하는 브로커를 통해 고정 기간의 무담보 대출을 확장합니다. 예금자는 금고에 지분을 보유하고 있으며, 이를 뒷받침하는 자산이 손실을 입으면 그 가치는 하락합니다. 풀링된 자산은 XRP, 트러스트 라인 토큰 또는 다목적 토큰(MPT)일 수 있습니다.
문서화된 규칙과 일치를 사용하여 즉시 기록하는 암호화폐 Slate의 비교 모델3. 3. 0 릴리스 코드, 8월 6일 발표. 수치는 가정입니다. Lending ProtocolV1_1이 개발 중인 것으로 표시된 9월 6일 확인된 공식 수정 레지스트리에서 메인넷 활성화가 확인되지 않았습니다. 예비 대출 기관은 보호를 판단하기 위해 준비금 뒤의 대출 규모와 지급 설정이 필요합니다.
세 가지 필드가 보호를 관리합니다. Cover Available은 실제로 예치된 준비금입니다. 최소 보장 비율은 브로커가 부채에 비해 유지해야 하는 보장 금액을 설정합니다. 보장 비율 청산은 하나의 채무 불이행에 사용할 수 있는 최소 필수 보장 금액을 결정합니다.
지불금 계산에는 필요한 최소 보장이 사용됩니다. 기본 예에서 브로커는 200, 000개의 토큰을 예치했지만 최소 10%를 위해서는 100만 부채에 대해 100, 000이 필요합니다. 10% 청산율은 최소 100, 000개에 적용되어 10, 000개 토큰 한도를 생성합니다. XLS-66 사양은 메커니즘을 설명하며 고정된 대출 관리 구현은 실제로 사용 가능한 한도에 따라 지불 금액을 제한합니다.
For this model, whose computed amounts are all representable whole tokens:
지급된 커버 = 현재 브로커 부채 중 최소 × 최소 커버율 × 청산율, 연체된 대출 부채 및 사용 가능한 적립금입니다.
각 불이행 이후 브로커 부채는 불이행된 전체 금액만큼 감소합니다. 적립금은 금고에 입금된 금액만큼 떨어집니다. 다음 대출 지급액은 업데이트된 잔액을 사용하여 계산됩니다.
두 요율이 모두 10%인 경우 첫 번째 한도는 1, 000, 000 × 10% × 10% 또는 10, 000개 토큰입니다. 따라서 100, 000개 토큰 대출은 브로커가 전체 채무 불이행을 흡수할 만큼 충분한 예비 현금으로 시작했음에도 불구하고 10, 000개를 보장받고 90, 000달러의 금고 손실을 남깁니다.
비교에서는 이미 서로 다른 구조에서 시작된 두 개의 대출 도서를 사용합니다. 각각은 동일한 900, 000개의 부채 이행 토큰과 100, 000개의 채무 불이행 토큰을 보유합니다. 하나의 대출로 해당 채무 불이행을 보유합니다. 다른 하나는 각각 10, 000씩 10개의 대출금을 보유하고 있습니다.
원문 제목: XRP lending model leaves depositors with 90% of a bad loan’s loss despite reserves twice its size
With the same reserve and cover rates, one modeled default leaves 90,000 tokens of vault loss; ten smaller loans leave 4,500.
The value backing depositors' shares in a modeled XRP Ledger loan book falls by 90,000 tokens when one loan defaults, compared with 4,500 when the same 100,000 tokens of bad debt sits in ten smaller loans. Both books start with 1 million tokens of debt, a 200,000-token reserve and identical protection settings.
The 20-fold gap comes from how the documented lending rules release that reserve. Each default gets a separate cover calculation. Loan size therefore changes how much loss reaches depositors, even when the total unpaid debt and the capital available to absorb it stay the same at the outset.
XRPL'slending designpools assets in a vault and extends fixed-term, uncollateralized loans through a broker responsible for underwriting. Depositors holdshares in the vault, whose value falls when the assets backing them suffer losses. The pooled asset can be XRP, a trust-line token or a Multi-Purpose Token (MPT).
CryptoSlate's comparison models that immediate write-down using documented rules and matching3.3.0 release code,announced Aug. 6. The figures are hypothetical. Mainnet activation was unconfirmed in the officialamendment registrychecked Sept. 6, which listed LendingProtocolV1_1 as in development. Prospective lenders need the loan sizes and payout settings behind a reserve to judge its protection.
Three fields govern the protection. CoverAvailable is the reserve actually deposited. CoverRateMinimum sets how much cover the broker must maintain relative to its debt. CoverRateLiquidation determines how much of that minimum required cover can be used for one default.
The payout calculation uses minimum required cover. In the base example, the broker has deposited 200,000 tokens, but the 10% minimum requires 100,000 against its 1 million of debt. The 10% liquidation rate applies to that 100,000 minimum, producing a 10,000-token cap. TheXLS-66 specificationdescribes the mechanism, and thepinned LoanManage implementationalso caps the payment by the cover actually available.
For this model, whose computed amounts are all representable whole tokens:
Cover paid = the smallest of current broker debt × minimum cover rate × liquidation rate, the defaulted loan's debt, and available reserve.
After each default, broker debt falls by the full amount defaulted. The reserve falls by the amount paid into the vault. The next loan's payout is calculated using those updated balances.
With both rates at 10%, the first cap is 1,000,000 × 10% × 10%, or 10,000 tokens. A 100,000-token loan therefore gets 10,000 of cover and leaves 90,000 of vault loss, even though the broker began with enough reserve cash to absorb the entire default.
The comparison uses two loan books that were already originated in different structures. Each has the same 900,000 tokens of performing debt and 100,000 of debt that defaults. One holds that defaulting debt in a single loan; the other holds it in ten loans of 10,000 each.